How Invoice Factoring Helps Businesses Improve Cash Flow Without Taking on More Debt
Waiting 30, 60, or even 90 days for customers to pay can put unnecessary pressure on your business. Invoice factoring converts unpaid invoices into immediate working capital, helping you cover payroll, purchase inventory, and take on new opportunities without adding traditional debt.
How Invoice Factoring Helps Businesses Improve Cash Flow Without Taking on More Debt
Cash flow is one of the biggest challenges growing businesses face. Even profitable companies can struggle to cover payroll, purchase inventory, or accept new projects when customers take 30, 60, or 90 days to pay their invoices. Instead of waiting for payments to arrive, invoice factoring provides immediate access to working capital by advancing cash against your outstanding receivables.
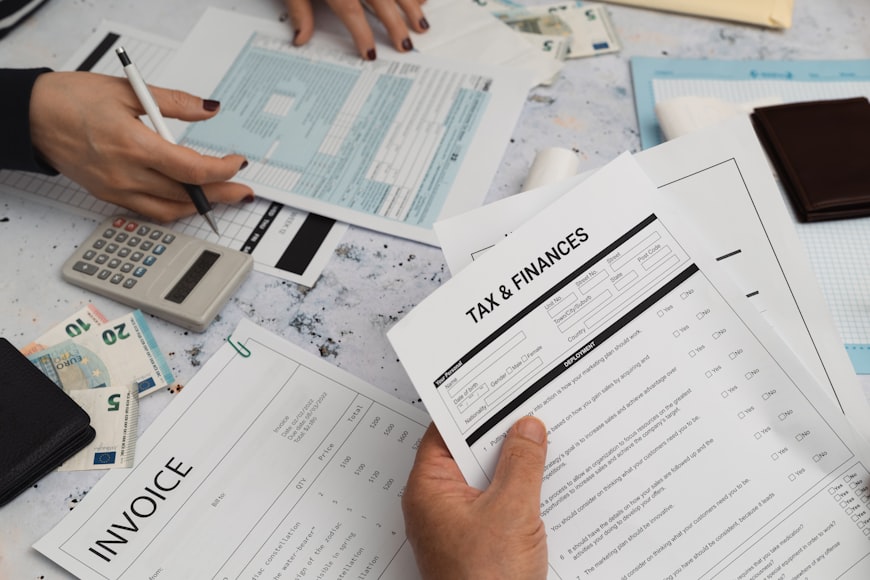
Unlike a traditional bank loan, invoice factoring isn’t based primarily on your business’s credit history or profitability. Instead, funding is secured by your unpaid invoices, allowing businesses to unlock cash that is already tied up in accounts receivable. This makes factoring an effective solution for companies experiencing rapid growth, seasonal demand, or extended customer payment terms.
One of the greatest advantages of invoice factoring is flexibility. As your sales increase, your available funding can grow as well because financing is directly linked to the value of your invoices. Rather than being limited by a fixed line of credit, businesses can access additional working capital as they generate more receivables.
The funds received through factoring can be used for virtually any business expense, including payroll, inventory purchases, equipment, marketing, fuel costs, supplier payments, or taking on larger customer contracts. Having predictable cash flow allows business owners to focus on growth instead of worrying about delayed payments.
For many businesses, factoring also simplifies accounts receivable management. Depending on the program, the factoring company may assist with invoice collections and payment processing, reducing administrative work while maintaining professional communication with your customers.
Industries such as staffing, transportation, manufacturing, wholesale distribution, construction, and professional services commonly use invoice factoring because they frequently operate with long payment cycles while needing immediate cash to support daily operations.
If your business has strong customers but experiences slow invoice payments, invoice factoring can provide a practical alternative to traditional financing. By turning outstanding invoices into working capital, you gain the financial flexibility to invest in growth, meet operational expenses, and confidently pursue new opportunities without taking on additional debt.
Whether you’re looking to bridge temporary cash flow gaps or build a long-term funding strategy, invoice factoring offers a fast, flexible, and scalable financing solution that grows alongside your business.
Common Questions
Questions Broad Search Readers Usually Ask Next
These questions are written for someone who is still understanding whether factoring fits a service business model at all, not someone already at the final decision stage.
Get in touchCan service businesses really use invoice factoring?
Yes, if they bill other businesses or institutions and those invoices qualify. Factoring is common in service models where the work is completed well before the client pays.
Is factoring only for staffing companies?
No. Staffing is a strong use case because payroll timing is acute, but consulting firms, agencies, project-based service businesses, and firms serving enterprise or government clients may also qualify.
Will my clients know if I use factoring?
A Notice of Assignment is typically part of the process, which means the payer is directed where to send funds. That is why the way collections and communication are handled matters so much. For higher-sensitivity use cases, see the staffing and professional services pages for more context.
How is this different from a line of credit?
Factoring is tied to receivables already issued, while a line of credit is a debt facility with its own underwriting and covenant dynamics. If that comparison matters for your business, the factoring vs. line of credit guide is the better next read.
Live Capital Markets
If the Receivables Gap Is Real, Take the Next Step Lightly
You do not need to jump straight from an informational article to a hard sales action. Start with the calculator if you want numbers first, or request a proposal if you already know timing is limiting growth.
- No commitments
- No hidden fees
- No personal guarantee required